The Projection — a symmetric watercolor butterfly

The Projection

The surface is never the system.

Global Capital

AI Bear Turn

Is the tape turning against the AI trade as a whole? Distinct from the circular-financing mechanics (Ben, 2026-07-27: "it's its own thing") — this tracks the market's aggregate verdict: the AI-heavy index into bear territory (07-27), the Mag7 -$797B day (07-23), SpaceX ~50% off its high, soft demand on AI-infra debt, hike odds rising. Track breadth (is it AI-specific or macro), the earnings verdicts, and whether the drawdown changes actual capex behavior.

STATUS · OPEN OPENED · 2026-07-27 LAST SEEN · 2026-09-04

Summary

This morning's premarket session is testing whether the AI trade's bear turn continues now that last night's earnings verdict is in.

Whether this morning's premarket reaction confirms the bear turn as AI-specific or signals a broader macro rotation is still unresolved.

2026-09-04 — Chip stocks decouple from broader tech, rallying as September hike odds cross 60%

2026-09-02 — A partial morning bounce, even as yields hit a fresh multi-year high

2026-09-01 — The Nvidia-earnings relief rally gives way to a fresh pullback, driven by Iran and AI-debt-linked yields

2026-08-31 — The oil/Fed-driven risk-off froze rather than deepened or reversed through the session’s first four hours

2026-08-26 (after close) — The earnings verdict this thread has been waiting for lands decisively bullish

2026-08-25 — Nvidia’s longest losing streak since 2022 runs into its own CEO’s admission that AI hasn’t found mass-market adoption yet

2026-08-24 — The bear turn shows up in prices: a broad semiconductor selloff two days before Nvidia’s print

2026-08-23 — Burry puts a fresh “lights out… 100% circular” call on the record two days before Nvidia’s print

2026-08-19/20 — Fund managers turn more bullish even as bond yields hit 2007 highs; a leveraged AI name falls 8.3% on a day the index rallied

2026-08-01 — July’s real number was the semis index, not the Nasdaq

2026-07-31 — July closes with the AI complex carrying the month’s losses almost alone

2026-07-30 (overnight) — The four prints landed: rewarded for returns, punished for the bet

2026-07-29 — FOMC holds 9-3, dissents replace unanimity, credit leg eases

2026-07-28 (overnight) — Korea rallies on the print, then breaks again

2026-07-28 (close) — the loud-no faded by the bell

2026-07-28 — FOMC eve: mixed tape, rate odds still elevated

2026-07-28 — Circuit breakers

2026-07-28 — The Seoul leg

2026-07-27 — Opened

This week's evidence

Nvidia opened higher while the broad market opened lower, which is the first real evidence on what Friday's selloff was actually about. NVDA opened around $219, up roughly 0.3–0.7% from Friday's $217.55 close, while the S&P 500 fell 0.45% to 7,677, the Dow 0.62% to 53,229 and the Nasdaq 0.43% to 26,290, on the Larak/Jordan/UAE exchange plus continued rate-hike repricing. This thread has carried two competing explanations for Friday's 4.74% Nvidia session — the vendor-financing pullback, or the hawkish Fed repricing. If financing were still the dominant driver, Nvidia would be expected to keep lagging; instead it is the outperformer against a macro-driven dip. ⚠️ One premarket and early session is not conclusive, and Micron, Intel and Broadcom are described in same-day coverage as choppy rather than clean movers either way. (CNBC, Yahoo Finance) 2026-08-31
The oil shock and the Fed repricing are pushing the long end the same way, not against each other. Brent above $90 on the Hormuz fighting raises the inflation path; the post-Jackson-Hole hike repricing raises the policy path. Both land on the same part of the curve, which is why the long end moved while equities did nothing all afternoon. 2026-08-31
Nvidia and the semiconductor index kept outperforming the tape into the afternoon, with Nvidia +0.62% and the SOX +0.06% against a −0.42% to −0.63% broad market. This strengthens the morning's own discriminator: if Friday's chip selloff had been principally about Nvidia's vendor-financing pullback, chips would be lagging on a risk-off day rather than leading it. They are leading it. 2026-08-31
The Nvidia-earnings relief rally gave way to a fresh pullback this morning: S&P 500 and Nasdaq-100 futures down roughly 0.3%, Nasdaq Composite off 1.1% intraday, Nvidia/AMD/Micron each down ~2%. Market coverage names the driver explicitly as the pairing of geopolitics with this map's own debt-risk thesis — "soaring AI corporate debt issuance added to credit supply and lifted yields further" — the same debt-into-yields mechanism AI Debt Gets Rated exists to track, now a same-day equity-market driver rather than a separate story. (Yahoo Finance/TheStreet) 2026-09-01
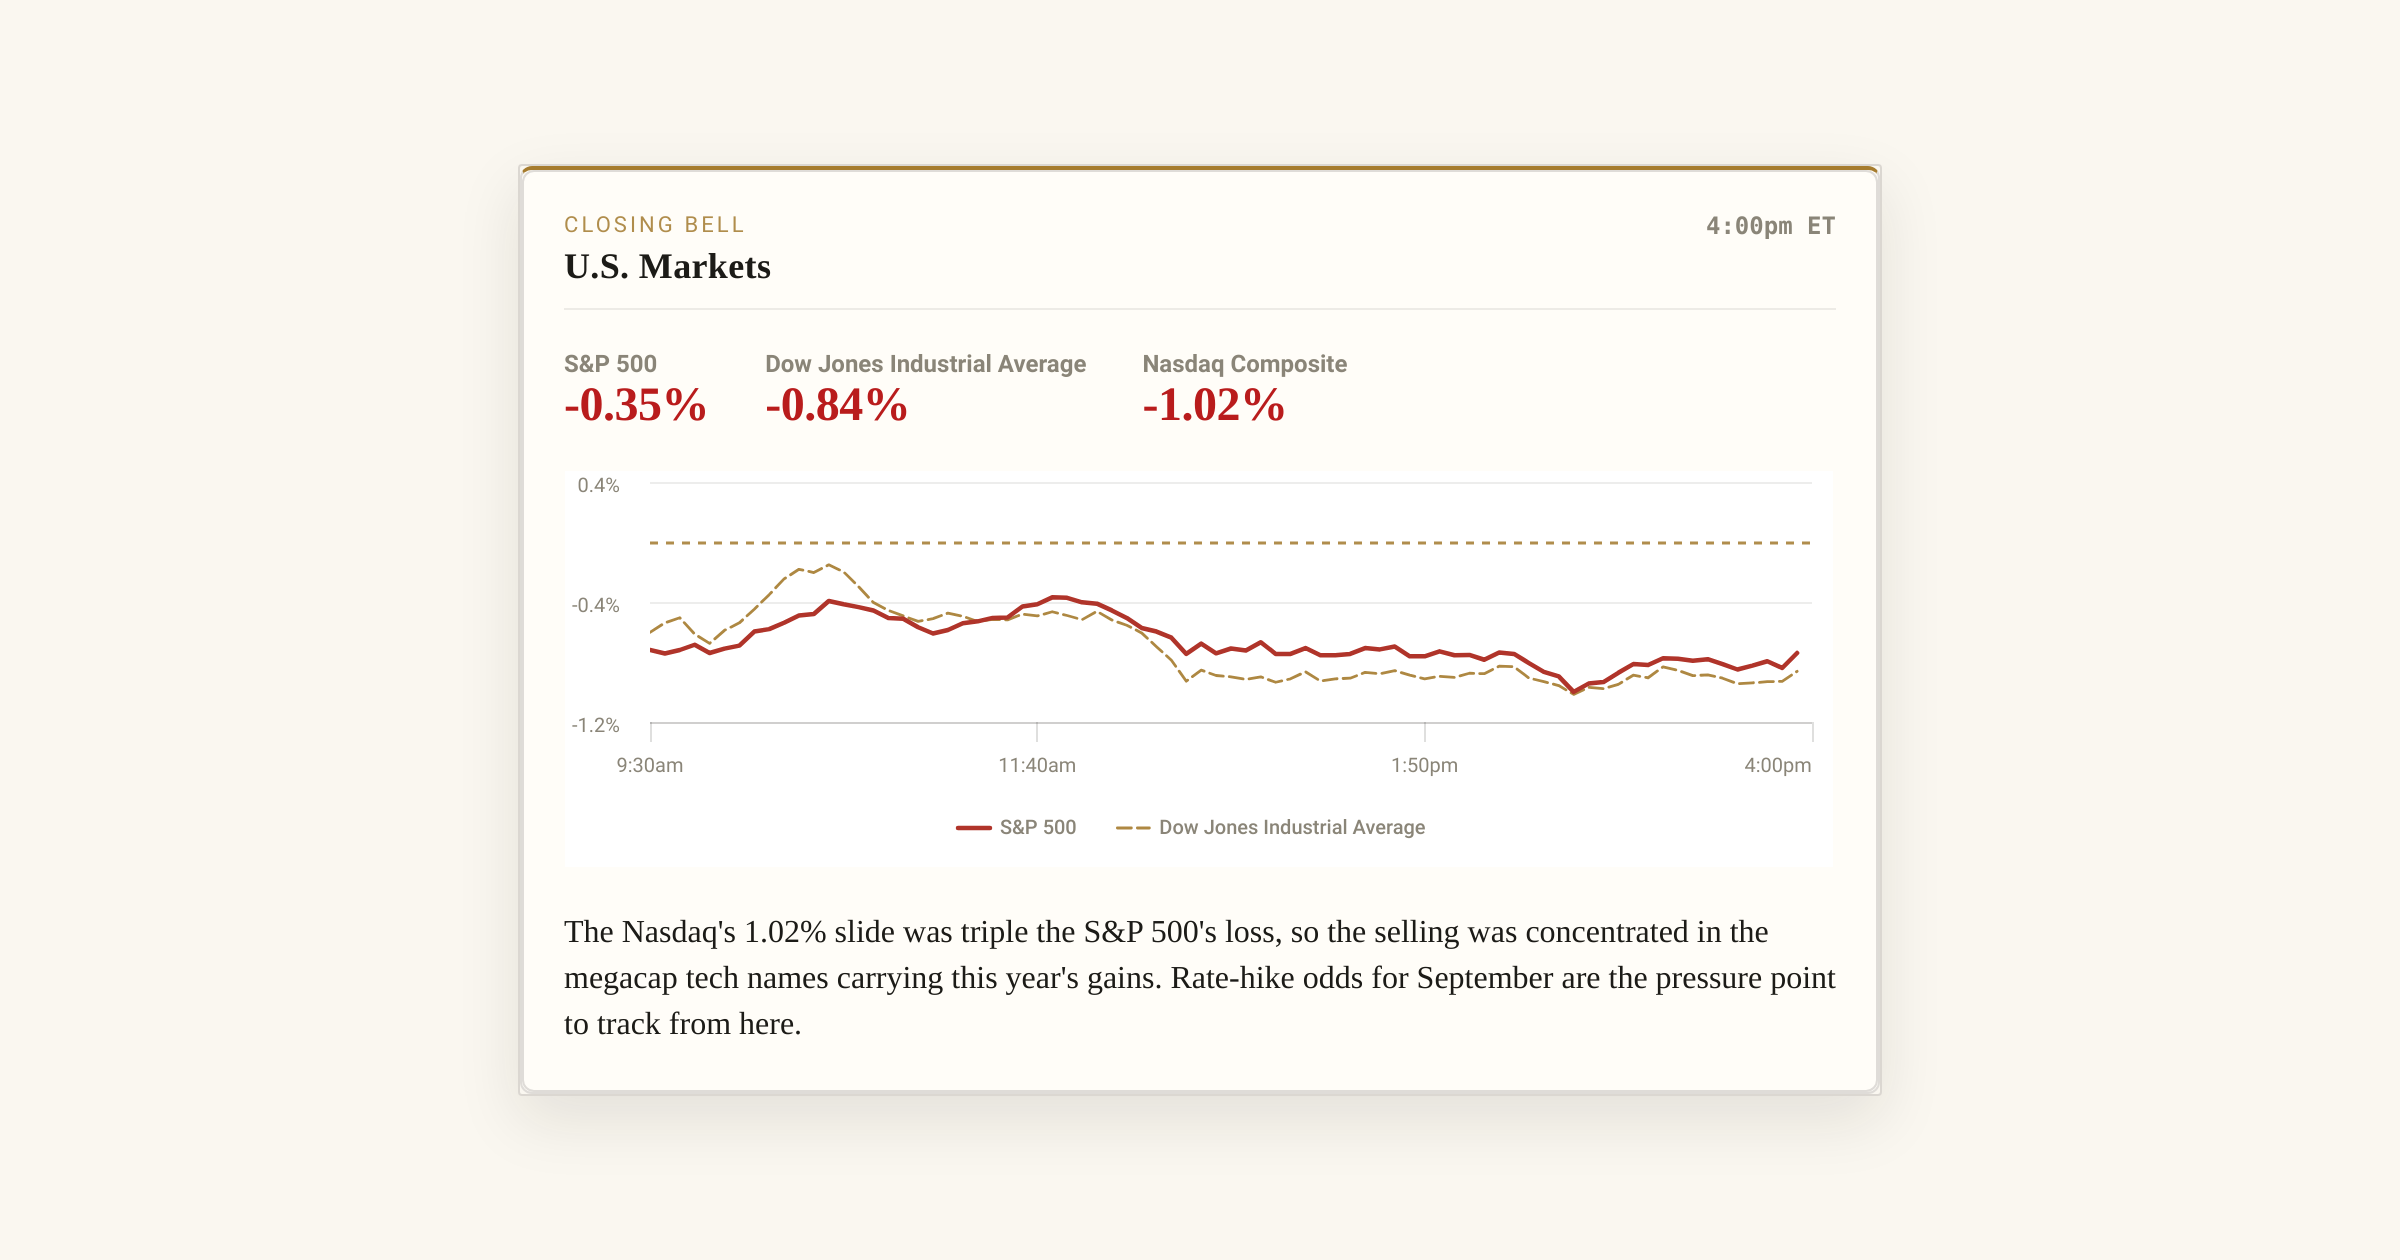
The indices closed down for a second straight session, deeper than the intraday read suggested: S&P 500 7,631.47 (-0.7%), Nasdaq Composite 26,099.77 (-1.0%), Dow 52,766.88 (-0.8%, -419pts). Nvidia itself closed $217.44, -1.51%. The causal read in the coverage is unchanged from this digest's own: rising oil and yields on the Iran conflict weighing on risk assets, with tech hit hardest — the Nasdaq's loss ran roughly triple the S&P's. (24/7 Wall St, stockanalysis.com, NVDA history) 2026-09-01
Stocks rose this morning despite the fresh multi-year yield high, then gave part of it back. Dow +330pts (+0.6%) to 53,097.79, S&P 500 +25.65 (+0.3%) to 7,657.12, Nasdaq +58.64 (+0.2%) to 26,158.42 in the morning session; by 14:35 ET the Dow's gain had narrowed to +247pts (+0.47%). WTI's October contract eased to $89.12 (-1.2%) on the same tape even as Brent's 8am read kept climbing. One analyst's read in the coverage: the modest gains suggest "investor optimism that escalation may lead to de-escalation" rather than a reversal of the underlying story. ⚠️ These are intraday levels, not a close — the session runs to 16:00 ET, past this window. Yesterday's digest made exactly this mistake and had to be revised on the finalize, so it is flagged rather than repeated. (Yahoo Finance) 2026-09-02
Thursday's data was mixed and did not move the tape: initial claims 206,000 against 205,000 expected (four-week average 207,250); ISM services 55.4 with business activity at 61.7 but employment contracting at 47.8; the July trade deficit $88.6bn with a $118.8bn goods gap, the widest since March 2025; Q2 productivity revised to +1.4% with unit labor costs +1.2%. Equities ran +1.1% to +1.4% across the three indices by late morning on the Waller-driven yield relief (Dow ~53,699, S&P ~7,754, Nasdaq ~26,572 at 11:46 ET), after Wednesday's closes of 53,061.95 / 7,666.60 / 26,217.83. (Yahoo Finance, market wrap) 2026-09-03
Chip stocks decoupled from the rest of tech intraday, rallying hard in the same session that pushed September-hike odds through 60% — the opposite of the rate-sensitivity reaction. On an 11:12am ET read: Intel +4% to $95.41, AMD +3% to $471.05, Nvidia +2% to $232.37, and the SOXX semiconductor ETF +3% to $517.91, against the Nasdaq-100 ETF QQQ essentially flat at +0.02%. A hawkish repricing should compress high-multiple names hardest; these led. The support cited is earnings rather than rates — Nvidia's most recent quarter at $96.22bn revenue (+105.8% y/y), AMD's Q2 at $11.54bn (+50.1% y/y) — and for Intel specifically the foundry turnaround pitch, though external foundry revenue is still only $293 million. This is intraday and not a close; the session runs to 16:00 ET. It sharpens the morning's "equities did not sell off" into something more specific: the resilience was concentrated in the AI cohort, not spread across the market. (24/7 Wall St.) 2026-09-04
Friday's chip-vs-tech decoupling survived the full session and shows up in the closing tape. The PHLX Semiconductor Index closed +3.38% at 11,735.26 while the S&P 500 (7,718.60, -0.38%), the Nasdaq Composite (26,506.99, -0.29%) and the Dow (53,414.25, -0.51%) all finished lower on the hot payrolls print. Rate-sensitivity logic said the high-multiple chip names should have been hit hardest by a hawkish repricing; at the close they were the only part of the tape that was up. ⚠️ Individual Intel, AMD and Nvidia closes are not stated because no closing-price page could be opened; the 11:12 ET intraday reads above are the last figures on record. (TheStreet, Yahoo Finance) 2026-09-04