Two distinct, simultaneous levers on the Fed's independence, offered as a thread candidate 08-07 and promoted 08-09 (Ben: "yes to all"). Composition lever: Trump revived his effort to remove Governor Lisa Cook on a hard three-week deadline (08-26), rebuilt to survive the Supreme Court's due-process ruling that blocked his first attempt — this map tracked two straight weeks of detailed FOMC vote-count coverage without ever naming her. Messaging lever: Chair Kevin Warsh's own forward-guidance-removal regime change is a separate, non-composition pressure on the same institution. Track: whether Cook's removal effort survives a second legal challenge before 08-26, and whether the Fed-composition fight becomes the dominant global-capital story into the 09-16 FOMC decision — as of the 08-09 /week read, a bigger open question than anything purely financial on this map.
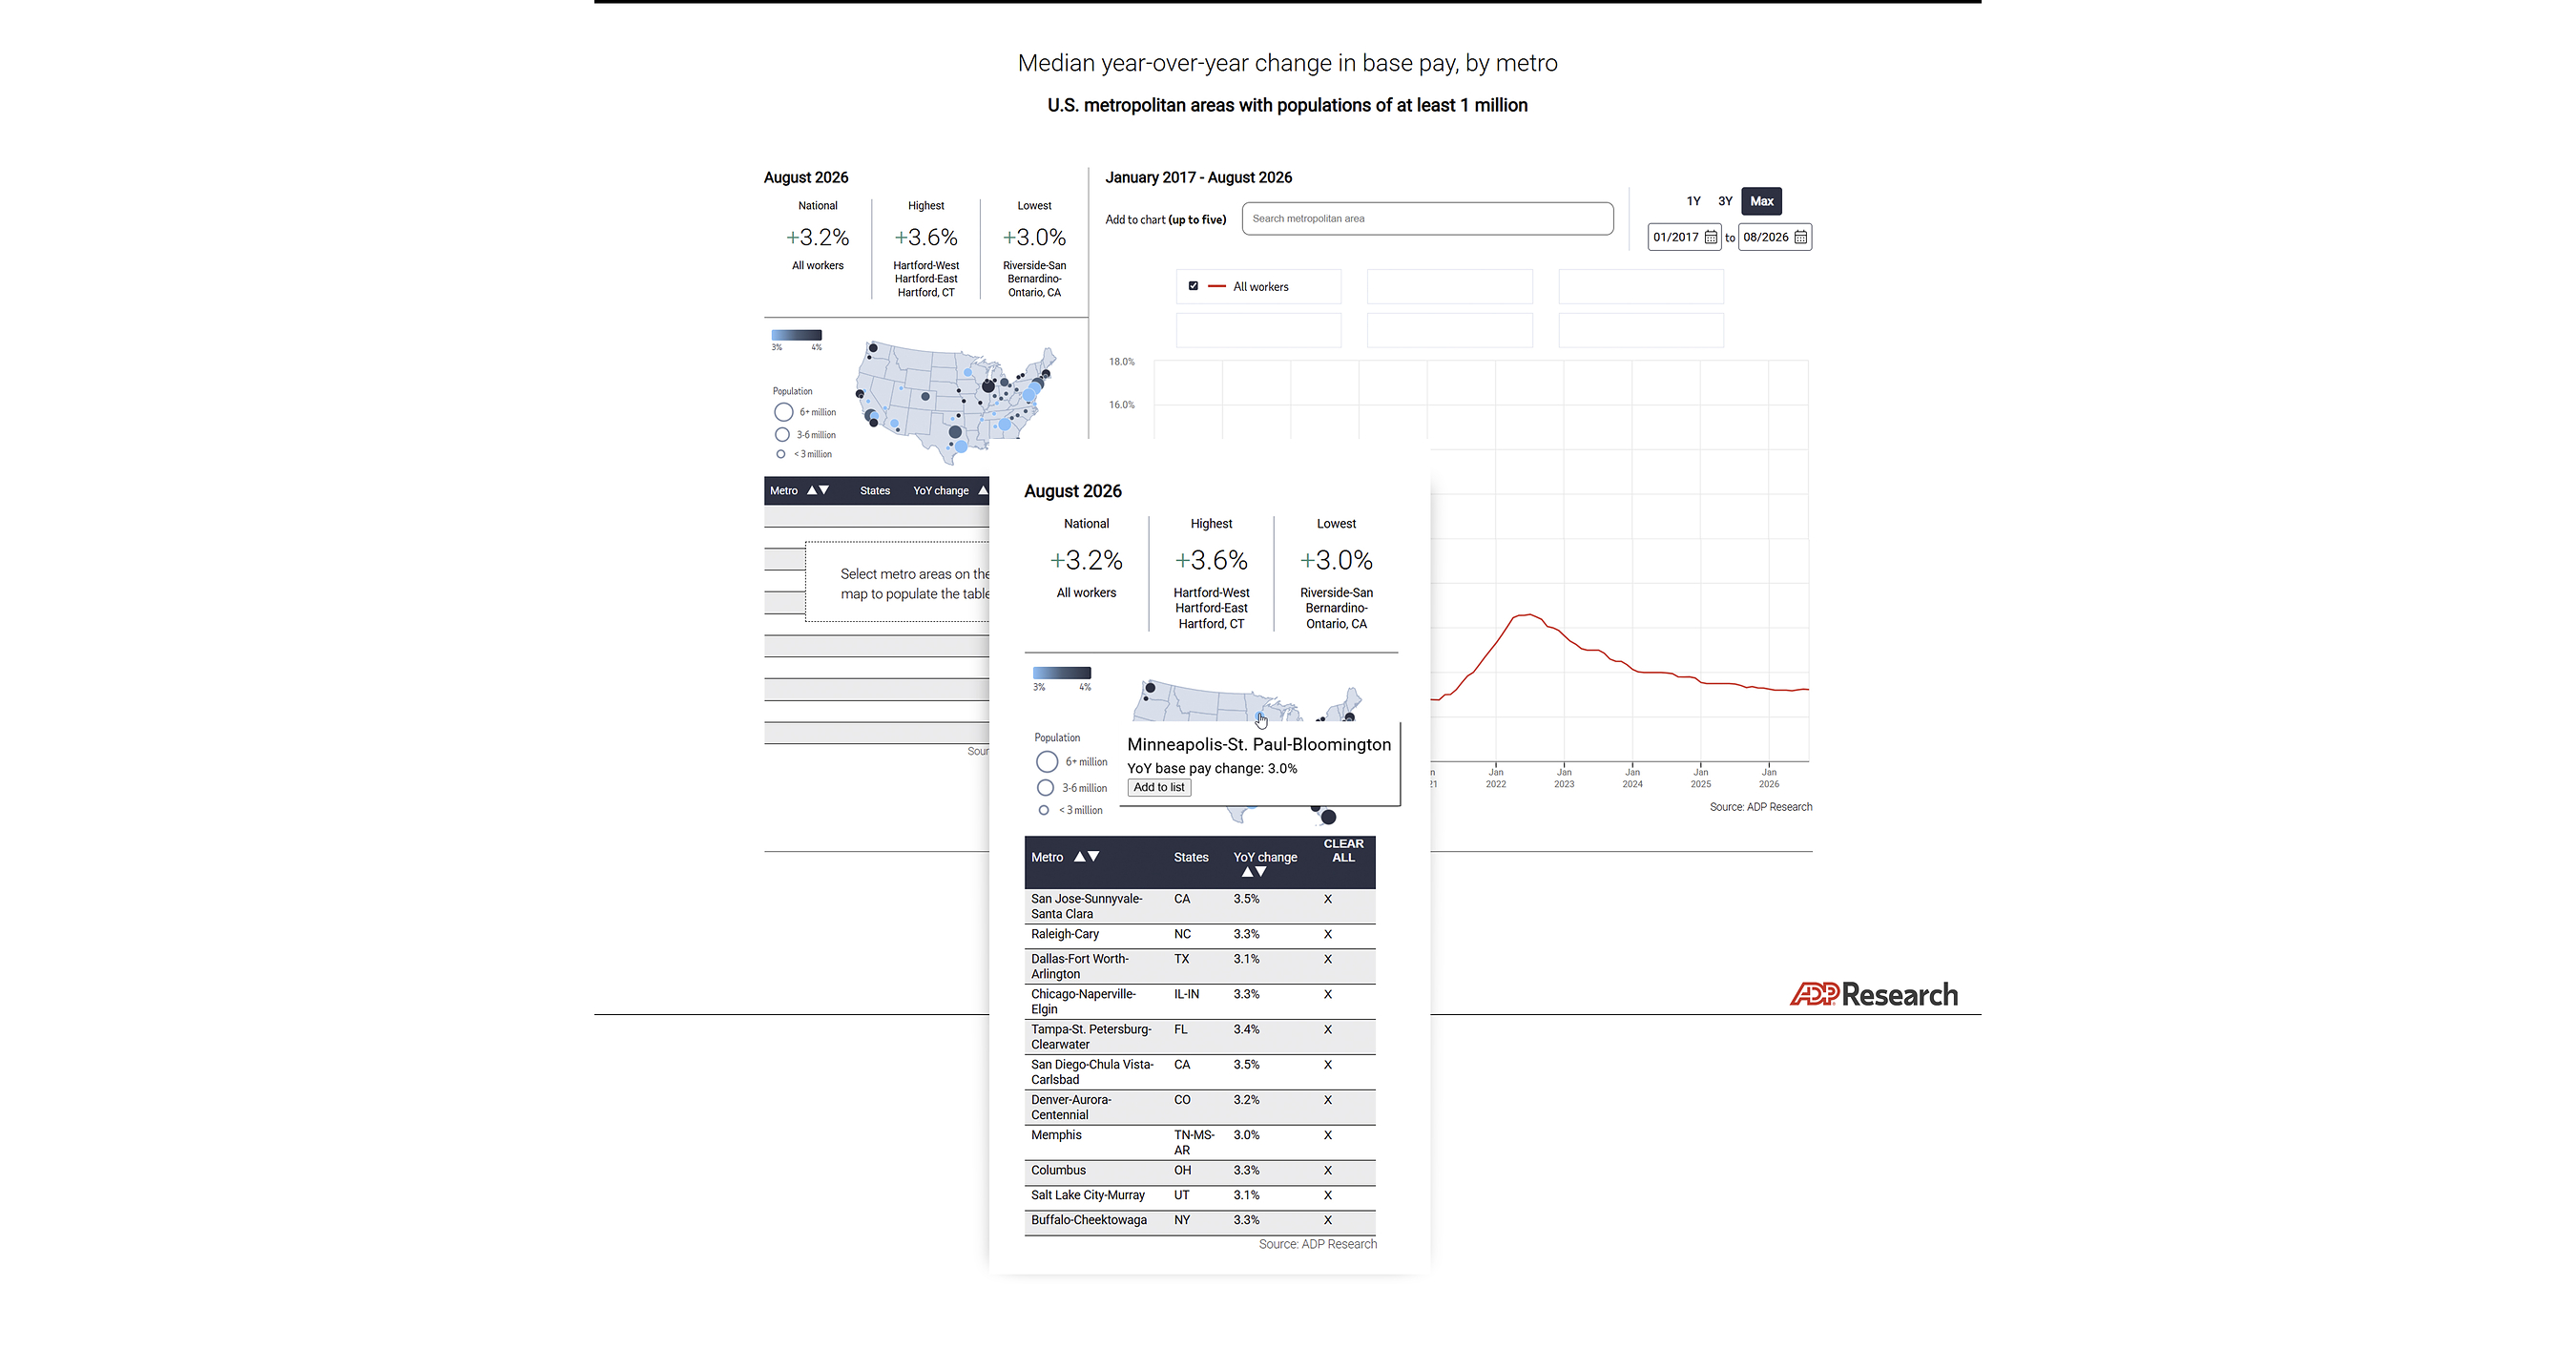
August nonfarm payrolls rose 162,000, roughly triple the ~50,000-55,000 consensus, with June and July revised up a combined 55,000 — July alone flips from an originally-reported -23,000 to +21,000 — directly testing the argument Governor Waller made in public less than 24 hours earlier. Unemployment held at 4.1%; average hourly earnings rose 0.3% m/m and 3.1% y/y, both in line. Waller said Wednesday he’d support a September hold “if disinflation continues… we can wait one meeting,” and CME September-hike odds fell to ~54.6% on that comment. Friday’s print reversed roughly half that move: hike odds rose back to an estimated 58-60% by mid-morning, the 2-year Treasury yield jumped 8bp to break 4.416% (its highest since January 2025), the 10-year rose to ~4.77%, and the dollar index rebounded off its weekly low (~98.92 to ~99.3). Equities were roughly flat to slightly lower (S&P ~-0.05%, Dow ~-0.16%, Nasdaq ~+0.09%) rather than selling off outright. The practical effect: the internal Fed argument this thread tracks — a Warsh-chaired, increasingly hawkish committee against a governor publicly arguing to wait — now has a real data point cutting toward Warsh’s side, one day after Waller staked out the opposite position in public. (BLS, Employment Situation Summary — August 2026, Yahoo Finance market wrap, Convera FX research)
Trump posted on Truth Social at 9:56am ET, minutes after the August jobs report, demanding the Fed cut rates — “The Fed Board, with its great new leader, must get smart - BE PATRIOTS for a change,” adding “High interest rates put the U.S.A. at a very unfair disadvantage, and I won’t allow that to happen!” and a trade threat: “LOWER THE RATE OR I’LL STOP TRADING WITH COUNTRIES WITH WHICH WE HAVE A DEFICIT.” This is the messaging-lever pressure this thread tracks, arriving the same morning the data moved against a cut and one week after Chair Kevin Warsh told the Jackson Hole symposium the Fed had “work to do” on above-target inflation — the two men are now pulling in opposite directions on the same rate decision. Coverage explicitly notes Trump “has refrained from excoriating Warsh personally for not [cutting], as he did with Warsh’s predecessor Jerome Powell” — a deliberate contrast in tone from the Cook-removal composition fight this same thread also tracks. (24/7 Wall St., Washington Times, The Spokesman-Review/AP)
As of 08-29, no primary or major-wire source confirms any White House or Trump response to Lisa Cook’s 08-26 written rebuttal — the Fed’s own press-release log is silent on Cook through today. This is itself informative against this thread’s own watch question: three days after the deadline-day letter, the removal effort has not visibly advanced.
⚠️ A single lower-tier aggregator (Guardian Nigeria, not the UK paper of the same name) carried a headline dated 08-28 22:43 GMT reading “Trump orders dismissal of Federal Reserve Governor Lisa Cook.” No corroboration was found from Reuters, AP, Bloomberg, NYT, WSJ, CNBC, PBS or Axios. Logged as an unconfirmed lead needing a primary-source check, not as fact — if real, it would be the next hard step after Cook’s 08-26 letter; if not, it’s a mislabeled or stale republish.
Kevin Warsh used his first Jackson Hole keynote as chair, on his hundredth day, to argue for a quieter Fed and to think out loud about artificial intelligence — and said nothing at all about the fight over the Fed’s independence. “In Our Time,” delivered 10:00 ET, opens by calling its own outline “a trail map . . . just don’t call it forward guidance,” argues the practice “has overstayed its welcome” outside crises, and declines a reaction function outright: “I wish our understanding of the economy were so precise… that some simple function like a Taylor rule could be rigorously relied upon. But our knowledge just doesn’t extend that far.” On the mandate he was direct — 12-month PCE 3.7%, six-month 4.1%, “running above our 2 percent target,” labour markets “consistent with full employment” — and he treated the 2% goal as firm and fixed, with “average inflation” absent from the text entirely. The absence is the finding for this thread, and it was verified rather than inferred: direct string search over the released text returns zero occurrences of “independence,” “administration” or “buyback.” Going in, previews framed the Cook removal fight and fiscal-dominance pressure as the market’s central question. He did not engage either. A chairman declining to defend the institution’s independence from the one podium built for it is a datapoint on this thread, not an empty result. (Federal Reserve, released text)
The University of Michigan’s final August survey put sentiment at 51.7, confirming its early-month reading, about 6% below July’s 55.2 and 11% below a year ago — with year-ahead inflation expectations falling to 4.0% from 4.2% and long-run expectations holding at 3.3% for a third month. The market moved on rhetoric against the data, repricing toward fewer cuts on the same day the only inflation-expectations print available softened. Expected year-ahead business conditions fell 10% and the five-year horizon 13%; the survey names the Iran conflict as driving gasoline-price expectations and notes 4.0% still “substantially exceeds the 3.4% seen in February before the Iran conflict began.” Interviews ran 07-28 to 08-24, so the window contains none of the keynote. ⚠️ A sweep reported this figure as rising to 4.3%; corrected against the primary release before publication. (University of Michigan, Surveys of Consumers, read directly)
Alan Blinder, a former Federal Reserve vice chairman now at Princeton, went on the record 08-28 (5:36pm ET) calling Warsh’s Jackson Hole remarks forward guidance in substance, despite Warsh’s own explicit disclaimer of the term. Blinder: “I would call that forward guidance,” adding Warsh “sounded to me like somebody who thought interest rates should go up, right?” and that Warsh sounded “like a man who was rationalizing raising interest rates.” This is a named, on-record contradiction of Warsh’s own framing from someone who held the job — a sharper, more citable version of the “the absence is the finding” read this thread already carries, and it lands on the same day the Fed’s own press-release log stayed silent on Cook. (Yahoo Finance / syndicated)
Chicago Fed President Austan Goolsbee, interviewed by Odd Lots at Jackson Hole on 08-27 and published 08-28 at 13:23 ET, said he is worried the economy is overheating, that the 2% target is “farther away than it was this time last year,” and that GDP is growing “mostly due to AI and the data center buildout” while hiring and firing both stay unusually low. He also said he is “embracing Kevin Warsh’s philosophy around reducing forward guidance.” Two things this thread did not have from the keynote day: a second Fed voice at the same venue endorsing the quieter-Fed doctrine, and a sitting Fed president attributing output growth itself to the buildout this map tracks — which is the Warsh AI section restated as a current-conditions claim rather than a research question. ⚠️ Critic-caught from the Odd Lots weekly benchmark; recorded from the episode transcript, not a Fed release. (Odd Lots, episode page and transcript)